Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
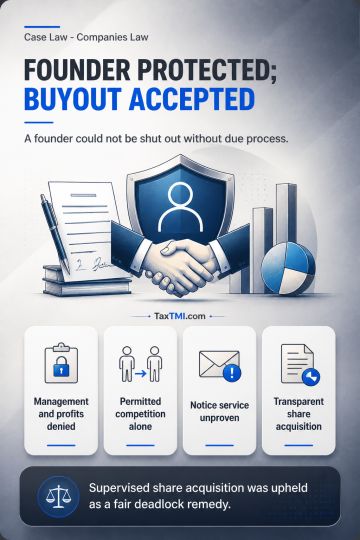
Oppression in a quasi-partnership family company arises where a founder and substantial shareholder is excluded from management and profit-related benefits without due process or justification. Permitted competition under an exit settlement, absent misuse of company data or employee solicitation, did not justify exclusion. In the absence of proof that board-meeting notices or minutes were served, non-attendance did not establish vacation of the directorship. The oppression finding was therefore sustained. Although the articles contained pre-emptive transfer rights, an independently supervised Swiss Challenge process for either shareholder group to acquire the other's shares substantially met their purpose and was upheld as a fair, transparent remedy for irretrievable breakdown of trust.
Oppression in a quasi-partnership family company arises where a founder and substantial shareholder is excluded from management and profit-related benefits without due process or justification. Permitted competition under an exit settlement, absent misuse of company data or employee solicitation, did not justify exclusion. In the absence of proof that board-meeting notices or minutes were served, non-attendance did not establish vacation of the directorship. The oppression finding was therefore sustained. Although the articles contained pre-emptive transfer rights, an independently supervised Swiss Challenge process for either shareholder group to acquire the other's shares substantially met their purpose and was upheld as a fair, transparent remedy for irretrievable breakdown of trust.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881