Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
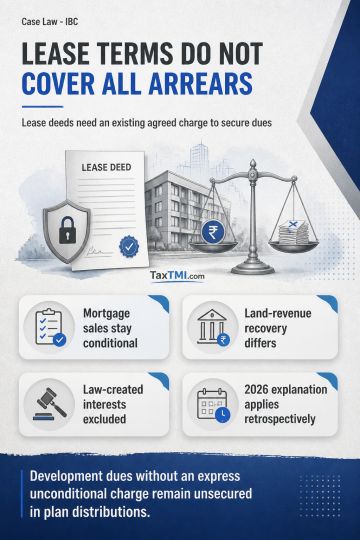
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881