Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
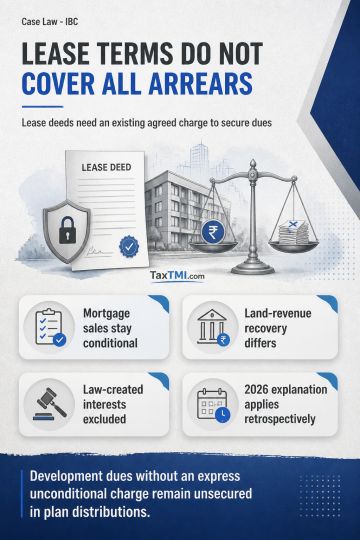
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881