Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
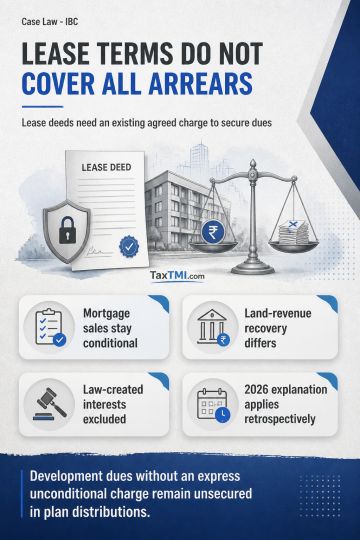
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881