Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
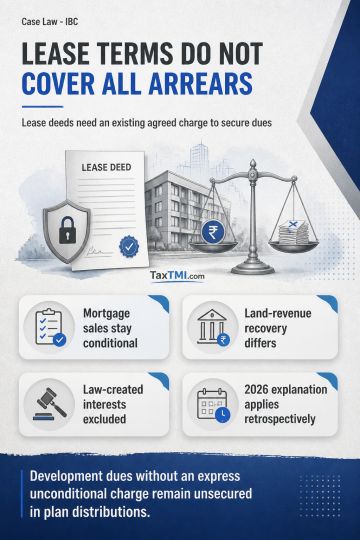
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881