Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Page of 4881
Press 'Enter' after typing page number.
341 to 360 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
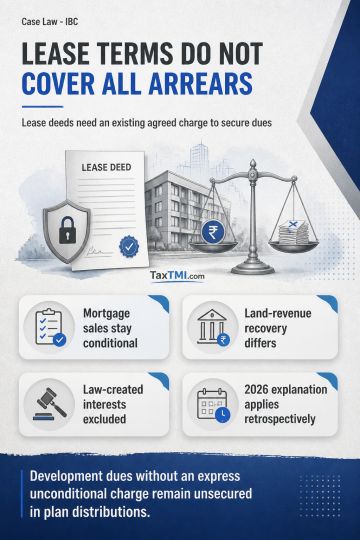
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Lease-deed mortgage provisions limited to the lessor's share in unearned increase, contingent on a mortgage sale or foreclosure, do not create a present general charge over all outstanding dues. A statutory power to recover arrears as land revenue is a recovery mechanism, not a consensual security interest. The 2026 Explanation excluding interests arising merely by operation of law is treated as clarificatory and retrospective. Accordingly, development authorities' dues lacking an express unconditional charge are classified as unsecured statutory or operational dues rather than secured debt under the resolution-plan distribution framework.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881