Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
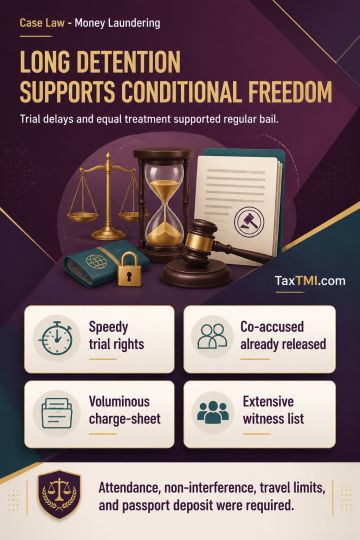
Prolonged pre-trial incarceration in money-laundering proceedings, assessed alongside the Article 21 right to a speedy trial, supported regular bail where a voluminous charge-sheet and extensive witness list made early commencement and conclusion of trial unlikely. Parity with a co-accused already released on bail further supported release. Regular bail was made subject to stringent conditions addressing attendance at trial, non-interference with evidence or witnesses, travel restrictions, and deposit of passports to mitigate risks of absconding or re-offending.
Prolonged pre-trial incarceration in money-laundering proceedings, assessed alongside the Article 21 right to a speedy trial, supported regular bail where a voluminous charge-sheet and extensive witness list made early commencement and conclusion of trial unlikely. Parity with a co-accused already released on bail further supported release. Regular bail was made subject to stringent conditions addressing attendance at trial, non-interference with evidence or witnesses, travel restrictions, and deposit of passports to mitigate risks of absconding or re-offending.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881