Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
Page of 4881
Press 'Enter' after typing page number.
541 to 560 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
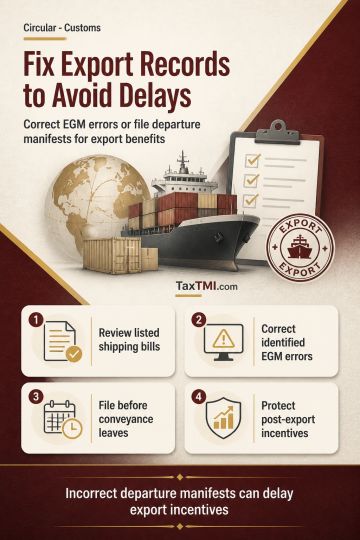
Export General Manifest errors identified in listed shipping bills require correction under the prescribed procedure, or filing of the relevant departure manifest, to enable post-export benefits and incentives. The person in charge of a conveyance carrying export goods must deliver a departure manifest to the proper officer before the conveyance leaves the customs station. Incorrect departure manifests can delay export incentives. Exporters, customs brokers, shipping lines, custodians and other concerned parties should rectify the identified EGM errors or file the required departure manifests.
Export General Manifest errors identified in listed shipping bills require correction under the prescribed procedure, or filing of the relevant departure manifest, to enable post-export benefits and incentives. The person in charge of a conveyance carrying export goods must deliver a departure manifest to the proper officer before the conveyance leaves the customs station. Incorrect departure manifests can delay export incentives. Exporters, customs brokers, shipping lines, custodians and other concerned parties should rectify the identified EGM errors or file the required departure manifests.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881