Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Page of 4881
Press 'Enter' after typing page number.
621 to 640 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
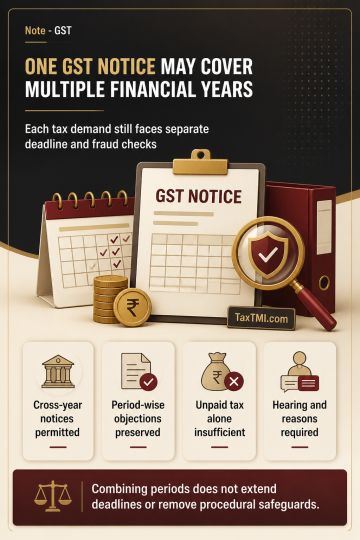
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881