Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
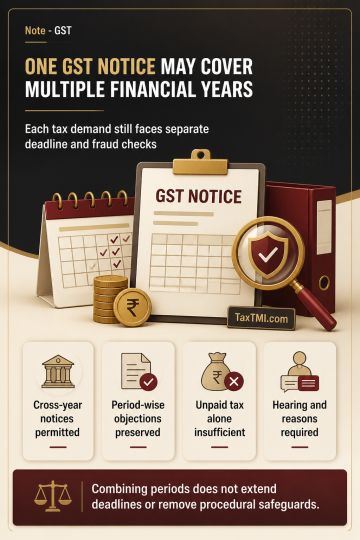
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881