Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
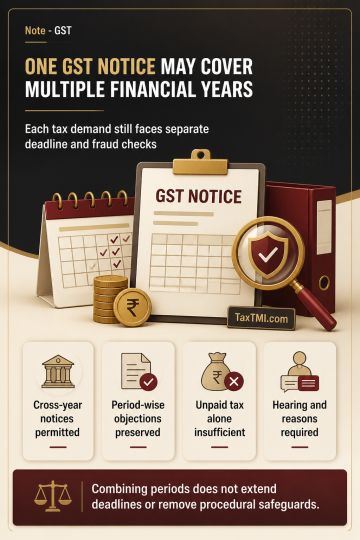
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884