Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Page of 4884
Press 'Enter' after typing page number.
261 to 280 of 97661 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
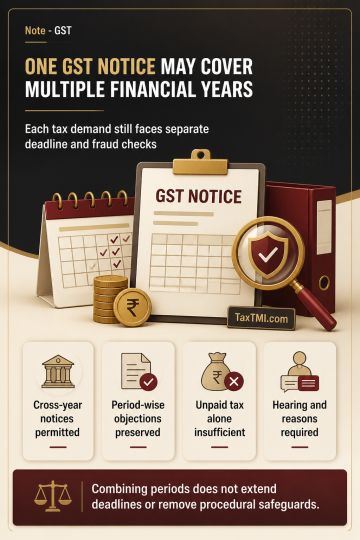
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884