Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
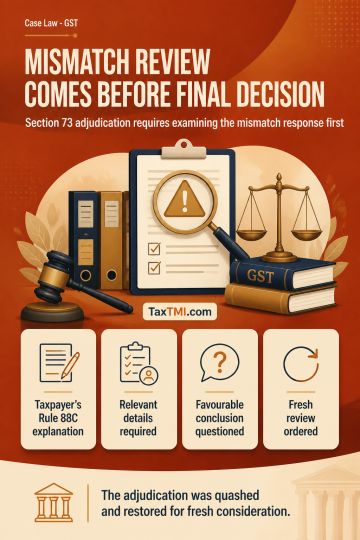
Section 73 adjudication requires consideration of the taxpayer's claim that its Rule 88C(2) explanation was accepted and that the mismatch proceedings concluded in its favour. Where that claim remains unexamined, the taxpayer must receive an opportunity to provide the relevant details and response. The adjudication was quashed and restored for fresh consideration of whether the Rule 88C proceedings had concluded in the taxpayer's favour and whether that conclusion affected the sustainability of the Section 73 proceedings.
Section 73 adjudication requires consideration of the taxpayer's claim that its Rule 88C(2) explanation was accepted and that the mismatch proceedings concluded in its favour. Where that claim remains unexamined, the taxpayer must receive an opportunity to provide the relevant details and response. The adjudication was quashed and restored for fresh consideration of whether the Rule 88C proceedings had concluded in the taxpayer's favour and whether that conclusion affected the sustainability of the Section 73 proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879