Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
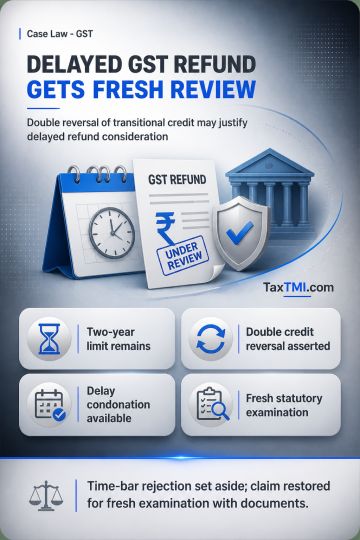
GST refund applications remain subject to a mandatory two-year limitation period, but writ jurisdiction may be available to condone delay. An asserted double reversal of TRAN-I credit, discovered only on examining records, can constitute just cause for such condonation. The time-bar rejection was set aside, and the refund claim was restored for fresh examination by the statutory authority upon production of supporting documents.
GST refund applications remain subject to a mandatory two-year limitation period, but writ jurisdiction may be available to condone delay. An asserted double reversal of TRAN-I credit, discovered only on examining records, can constitute just cause for such condonation. The time-bar rejection was set aside, and the refund claim was restored for fresh examination by the statutory authority upon production of supporting documents.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879