Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
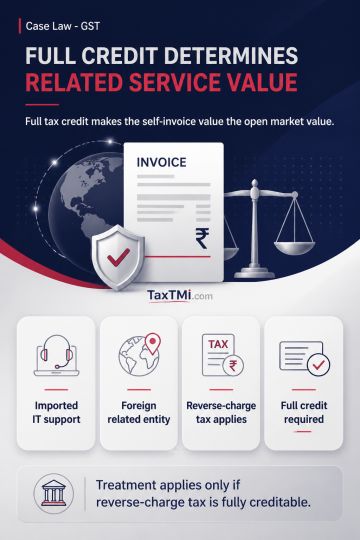
Imported IT support services from a related foreign entity constitute imports of services liable to integrated tax under reverse charge. For such supplies, the recipient's self-invoice qualifies as the invoice contemplated by the second proviso to Rule 28(1) and the reverse-charge self-invoicing requirement. Where the recipient is eligible for full input tax credit, the value declared in that self-invoice is deemed to be the open market value. This treatment applies only subject to full input tax credit eligibility on the reverse-charge tax payable.
Imported IT support services from a related foreign entity constitute imports of services liable to integrated tax under reverse charge. For such supplies, the recipient's self-invoice qualifies as the invoice contemplated by the second proviso to Rule 28(1) and the reverse-charge self-invoicing requirement. Where the recipient is eligible for full input tax credit, the value declared in that self-invoice is deemed to be the open market value. This treatment applies only subject to full input tax credit eligibility on the reverse-charge tax payable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937