Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
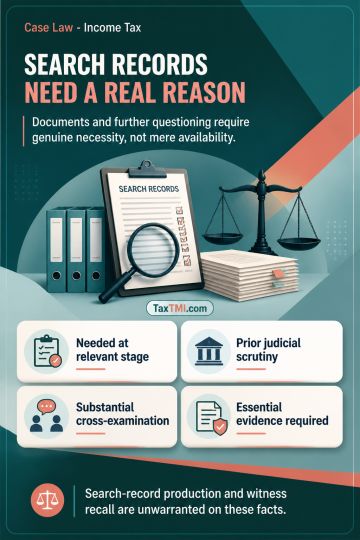
Section 91 CrPC permits compulsory production of search records only when they are necessary or desirable at the relevant stage, rather than merely because they exist or are available. Where the warrant and search procedures have already received judicial scrutiny on foundational material, no continuing necessity arises to compel the satisfaction note, authorisation warrant or panchnama solely to revisit the search's legality. Section 311 CrPC permits recall for further cross-examination only where further evidence is essential to a just decision. Recall is unwarranted when the material sought is not on record and the witness has already been substantially cross-examined on the relevant search-related allegations.
Section 91 CrPC permits compulsory production of search records only when they are necessary or desirable at the relevant stage, rather than merely because they exist or are available. Where the warrant and search procedures have already received judicial scrutiny on foundational material, no continuing necessity arises to compel the satisfaction note, authorisation warrant or panchnama solely to revisit the search's legality. Section 311 CrPC permits recall for further cross-examination only where further evidence is essential to a just decision. Recall is unwarranted when the material sought is not on record and the witness has already been substantially cross-examined on the relevant search-related allegations.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879