Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
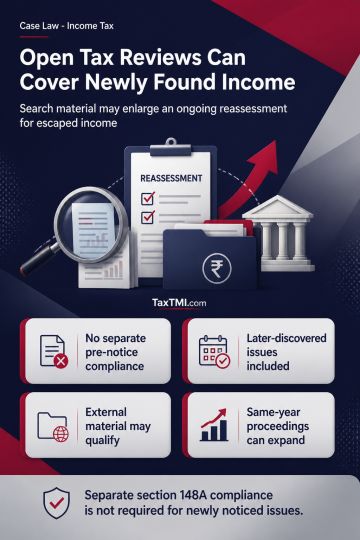
Explanation to amended section 147 permits an ongoing reassessment to be enlarged for any escaped-income issue subsequently noticed, without separate compliance with the section 148A procedure. Removal of "and also" from the substantive provision distinguishes prior interpretations of the unamended law. Its wording and context show legislative intent to expand rather than merely clarify reassessment scope. "Any issue" covers material obtained after commencement from sources outside the original proceedings, including search material. Authorities may use such material to enlarge a pending reassessment for the same assessment year, despite a separate search-assessment mechanism.
Explanation to amended section 147 permits an ongoing reassessment to be enlarged for any escaped-income issue subsequently noticed, without separate compliance with the section 148A procedure. Removal of "and also" from the substantive provision distinguishes prior interpretations of the unamended law. Its wording and context show legislative intent to expand rather than merely clarify reassessment scope. "Any issue" covers material obtained after commencement from sources outside the original proceedings, including search material. Authorities may use such material to enlarge a pending reassessment for the same assessment year, despite a separate search-assessment mechanism.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881