Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
Page of 4937
Press 'Enter' after typing page number.
1261 to 1280 of 98735 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
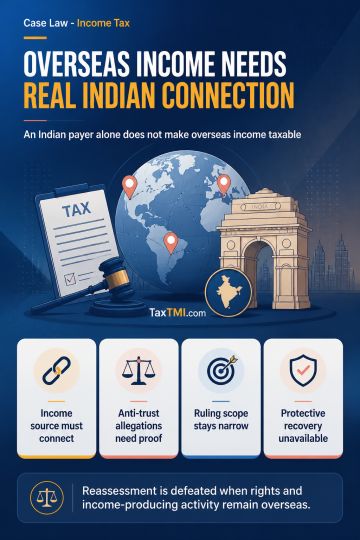
Taxability of non-resident receipts depends on a real and substantive nexus between India and the income-producing right or activity, or on a specific statutory deeming provision; an Indian payer's residence, accounting treatment, expenditure claim or remittance alone is insufficient. Overseas contractual rights, settlement and market exploitation do not create Indian accrual merely through foreign anti-trust allegations unsupported by a judicial finding or admission. Advance-ruling jurisdiction is confined to the applicant and transaction, and prima facie tax avoidance requires an identified Indian tax incidence. Extended reassessment limitation requires a qualifying asset belonging to the assessee and prior meaningful opportunity on that ground. Protective assessment may address uncertainty over the taxable person but cannot support protective recovery; TDS refunds may be secured pending substantive assessment.
Taxability of non-resident receipts depends on a real and substantive nexus between India and the income-producing right or activity, or on a specific statutory deeming provision; an Indian payer's residence, accounting treatment, expenditure claim or remittance alone is insufficient. Overseas contractual rights, settlement and market exploitation do not create Indian accrual merely through foreign anti-trust allegations unsupported by a judicial finding or admission. Advance-ruling jurisdiction is confined to the applicant and transaction, and prima facie tax avoidance requires an identified Indian tax incidence. Extended reassessment limitation requires a qualifying asset belonging to the assessee and prior meaningful opportunity on that ground. Protective assessment may address uncertainty over the taxable person but cannot support protective recovery; TDS refunds may be secured pending substantive assessment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937