Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
Page of 4881
Press 'Enter' after typing page number.
501 to 520 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Social forestry expenditure requires activity-based...
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additions do not increase tax.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
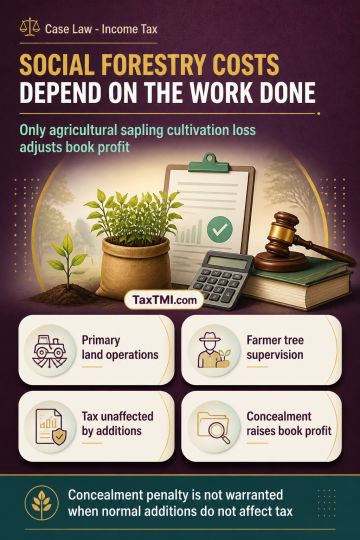
Social forestry expenditure requires activity-based classification: costs of growing saplings through primary land operations are agricultural, while supervision of farmers' trees and coppice shoots without primary land operations are business or non-agricultural expenditure. Disallowance is therefore confined to the loss from agricultural sapling cultivation. For book-profit computation, only that restricted disallowed agricultural loss may be adjusted, rather than all amortised social forestry expenditure. Where normal-computation additions do not affect tax because liability is based on book profit, no tax is sought to be avoided and concealment penalty is not warranted. Penalty may nevertheless arise if concealed income increases book profit and the resulting minimum alternative tax.
Social forestry expenditure requires activity-based classification: costs of growing saplings through primary land operations are agricultural, while supervision of farmers' trees and coppice shoots without primary land operations are business or non-agricultural expenditure. Disallowance is therefore confined to the loss from agricultural sapling cultivation. For book-profit computation, only that restricted disallowed agricultural loss may be adjusted, rather than all amortised social forestry expenditure. Where normal-computation additions do not affect tax because liability is based on book profit, no tax is sought to be avoided and concealment penalty is not warranted. Penalty may nevertheless arise if concealed income increases book profit and the resulting minimum alternative tax.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881