Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
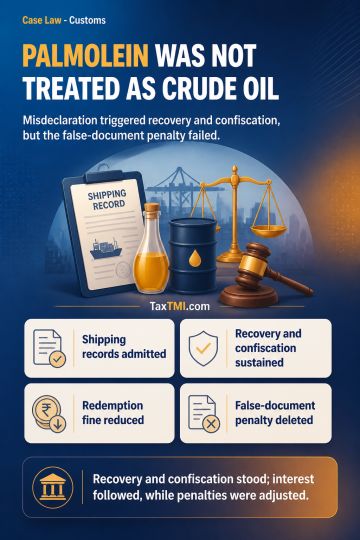
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
Contractual and decree-based rights to obtain conveyance of immovable property constitute capital assets, and their assignment is a transfer taxable under Capital Gains rather than Income from Other Sources. Indexed cost of improvement requires verification of supporting documents and was remanded for fresh examination. The residential-house exemption claim was also remanded for consideration of evidence on fund utilisation, land acquisition and Capital Gains Account Scheme transactions. In alleged penny-stock transactions, surrounding circumstances and preponderance of probabilities may outweigh contract notes, banking records and demat statements; the share-sale proceeds were sustained as unexplained cash credit and the capital-gains exemption was denied.
Contractual and decree-based rights to obtain conveyance of immovable property constitute capital assets, and their assignment is a transfer taxable under Capital Gains rather than Income from Other Sources. Indexed cost of improvement requires verification of supporting documents and was remanded for fresh examination. The residential-house exemption claim was also remanded for consideration of evidence on fund utilisation, land acquisition and Capital Gains Account Scheme transactions. In alleged penny-stock transactions, surrounding circumstances and preponderance of probabilities may outweigh contract notes, banking records and demat statements; the share-sale proceeds were sustained as unexplained cash credit and the capital-gains exemption was denied.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939