Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
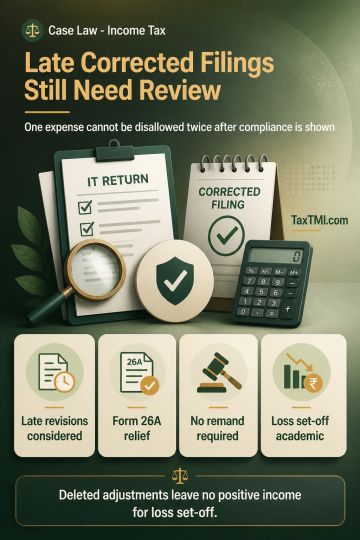
Revised tax audit reports and corresponding revised returns filed before processing under section 143(1) require consideration despite filing after the prescribed due date where they correct disallowances based on Form 26A. Form 26A activates statutory relief from disallowance for non-deduction of tax at source, and the same expenditure cannot be disallowed again under section 40(a)(ia) after disallowance under section 43B(da). Rule 46A(3) does not require remand when materials were electronically furnished before processing and no fresh appellate evidence is admitted. After deletion of adjustments, set-off of brought-forward losses is academic where no positive income remains.
Revised tax audit reports and corresponding revised returns filed before processing under section 143(1) require consideration despite filing after the prescribed due date where they correct disallowances based on Form 26A. Form 26A activates statutory relief from disallowance for non-deduction of tax at source, and the same expenditure cannot be disallowed again under section 40(a)(ia) after disallowance under section 43B(da). Rule 46A(3) does not require remand when materials were electronically furnished before processing and no fresh appellate evidence is admitted. After deletion of adjustments, set-off of brought-forward losses is academic where no positive income remains.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939