Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
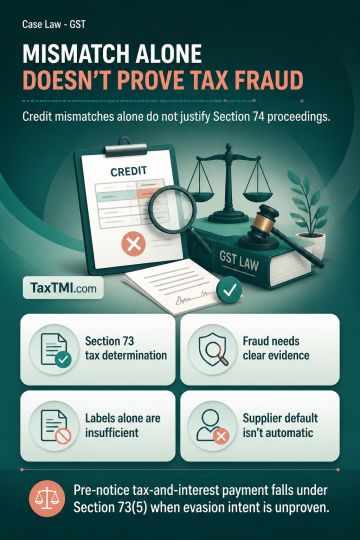
Input tax credit mismatches between Forms GSTR-3B and GSTR-2A may support tax determination under section 73, but do not by themselves justify section 74 proceedings or penalties. Section 74 requires clear evidence connecting wrongful credit availment with fraud, wilful misstatement, or suppression of facts intended to evade tax; merely reciting those terms is insufficient. Payment of tax and interest before notice, including after verification, falls within section 73(5) where no intent to evade is established. A supplier's default cannot automatically be attributed to the recipient as suppression.
Input tax credit mismatches between Forms GSTR-3B and GSTR-2A may support tax determination under section 73, but do not by themselves justify section 74 proceedings or penalties. Section 74 requires clear evidence connecting wrongful credit availment with fraud, wilful misstatement, or suppression of facts intended to evade tax; merely reciting those terms is insufficient. Payment of tax and interest before notice, including after verification, falls within section 73(5) where no intent to evade is established. A supplier's default cannot automatically be attributed to the recipient as suppression.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879