Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Rental income from let-out business premises cannot be increased...
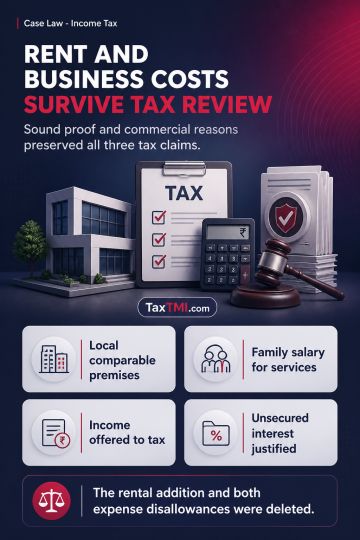
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deductible.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Rental income from let-out business premises cannot be increased by relying on rent from a commercial property at a different location without credible evidence that comparable local premises command higher rent; the estimated addition was deleted. Salary paid to a family member remains allowable where business services were rendered, payments were consistent, and the recipient offered the income to tax; the disallowance was deleted. Interest on unsecured business borrowings may exceed secured bank-loan rates where flexibility, short-term repayment terms, ancillary borrowing costs and commercial expediency establish that the rate is reasonable; the interest disallowance was deleted.
Rental income from let-out business premises cannot be increased by relying on rent from a commercial property at a different location without credible evidence that comparable local premises command higher rent; the estimated addition was deleted. Salary paid to a family member remains allowable where business services were rendered, payments were consistent, and the recipient offered the income to tax; the disallowance was deleted. Interest on unsecured business borrowings may exceed secured bank-loan rates where flexibility, short-term repayment terms, ancillary borrowing costs and commercial expediency establish that the rate is reasonable; the interest disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931