Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
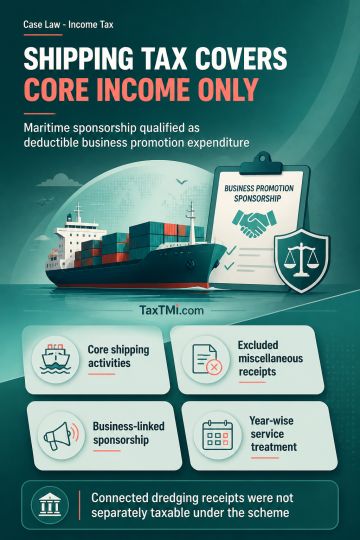
The Tonnage Tax Scheme confines relevant shipping income to profits from specified core and prescribed incidental shipping activities. Receipts from tender-document sales, contractor-delay damages, leased quarters, training fees, other operating income, and salary recoveries from resigned employees fell outside that scope, whereas scrap and empties sales, exchange differences, waste-oil sales, insurance claims, and provision reversals were treated as connected with dredging operations or not separately taxable. Service charges received differing treatment across assessment years in line with earlier determinations. Sponsorship for a maritime investment event qualified as business promotion expenditure because it had a direct business nexus and met commercial expediency, notwithstanding its accounting classification as donation; under the scheme, its debit or disallowance did not affect taxable-profit computation.
The Tonnage Tax Scheme confines relevant shipping income to profits from specified core and prescribed incidental shipping activities. Receipts from tender-document sales, contractor-delay damages, leased quarters, training fees, other operating income, and salary recoveries from resigned employees fell outside that scope, whereas scrap and empties sales, exchange differences, waste-oil sales, insurance claims, and provision reversals were treated as connected with dredging operations or not separately taxable. Service charges received differing treatment across assessment years in line with earlier determinations. Sponsorship for a maritime investment event qualified as business promotion expenditure because it had a direct business nexus and met commercial expediency, notwithstanding its accounting classification as donation; under the scheme, its debit or disallowance did not affect taxable-profit computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934