Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
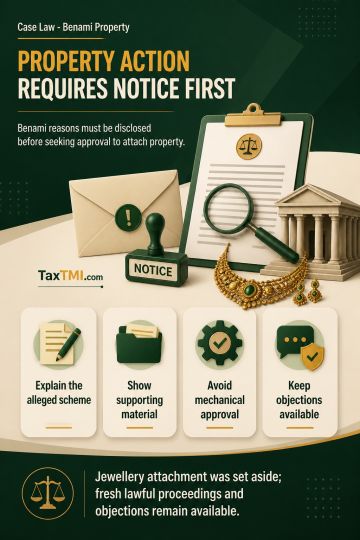
Section 24 requires the Initiating Officer to first issue notice to the alleged benamidar, disclose the reasons for believing the property is benami, and only then seek prior approval for provisional attachment. The Approving Authority must assess the notice and supporting material; approval obtained before notice is mechanical and contrary to the statutory scheme. Accordingly, the confirmed provisional attachment of the jewellery was set aside, while fresh proceedings in accordance with law and all available objections were left open.
Section 24 requires the Initiating Officer to first issue notice to the alleged benamidar, disclose the reasons for believing the property is benami, and only then seek prior approval for provisional attachment. The Approving Authority must assess the notice and supporting material; approval obtained before notice is mechanical and contrary to the statutory scheme. Accordingly, the confirmed provisional attachment of the jewellery was set aside, while fresh proceedings in accordance with law and all available objections were left open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932