Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
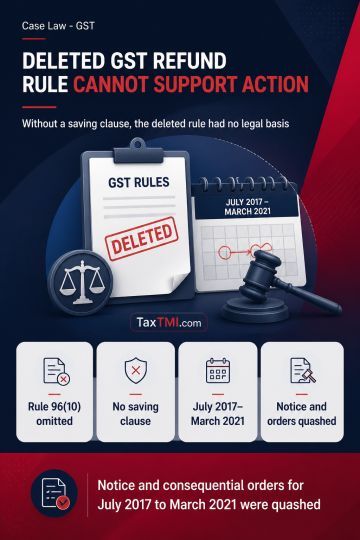
Unconditional omission of Rule 96(10) of the CGST/WBGST Rules, 2017, without a saving clause, rendered the rule nonexistent for proceedings founded solely on it. Applying Supreme Court law on the effect of such omission, the High Court found that the impugned proceedings had no independent statutory basis. The show-cause notice and consequential orders concerning July 2017 to March 2021 were therefore quashed, and the writ petition was disposed of.
Unconditional omission of Rule 96(10) of the CGST/WBGST Rules, 2017, without a saving clause, rendered the rule nonexistent for proceedings founded solely on it. Applying Supreme Court law on the effect of such omission, the High Court found that the impugned proceedings had no independent statutory basis. The show-cause notice and consequential orders concerning July 2017 to March 2021 were therefore quashed, and the writ petition was disposed of.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881