Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
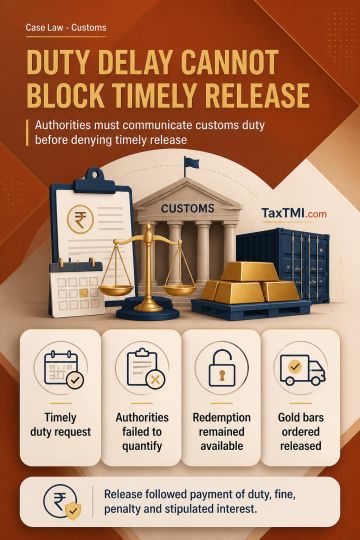
Redemption of confiscated goods remains available where the person seeking redemption timely requests quantification of applicable customs duty, but the authorities neither quantify it nor clarify that redemption fine and penalty may be paid independently. Failure to complete redemption within the stipulated period cannot then be attributed solely to the claimant, notwithstanding that expiry ordinarily makes confiscation absolute. The High Court directed communication of duty and release of the gold bars after payment of duty, redemption fine, penalty and stipulated interest.
Redemption of confiscated goods remains available where the person seeking redemption timely requests quantification of applicable customs duty, but the authorities neither quantify it nor clarify that redemption fine and penalty may be paid independently. Failure to complete redemption within the stipulated period cannot then be attributed solely to the claimant, notwithstanding that expiry ordinarily makes confiscation absolute. The High Court directed communication of duty and release of the gold bars after payment of duty, redemption fine, penalty and stipulated interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881