Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
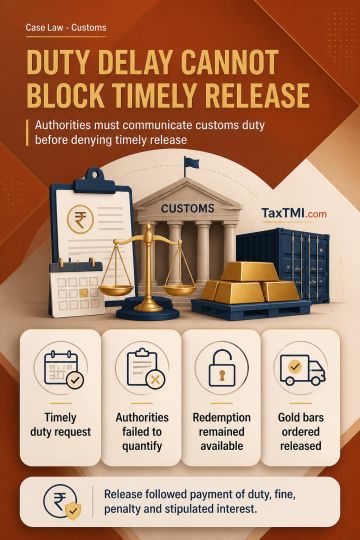
Redemption of confiscated goods remains available where the person seeking redemption timely requests quantification of applicable customs duty, but the authorities neither quantify it nor clarify that redemption fine and penalty may be paid independently. Failure to complete redemption within the stipulated period cannot then be attributed solely to the claimant, notwithstanding that expiry ordinarily makes confiscation absolute. The High Court directed communication of duty and release of the gold bars after payment of duty, redemption fine, penalty and stipulated interest.
Redemption of confiscated goods remains available where the person seeking redemption timely requests quantification of applicable customs duty, but the authorities neither quantify it nor clarify that redemption fine and penalty may be paid independently. Failure to complete redemption within the stipulated period cannot then be attributed solely to the claimant, notwithstanding that expiry ordinarily makes confiscation absolute. The High Court directed communication of duty and release of the gold bars after payment of duty, redemption fine, penalty and stipulated interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881