Composite GST notices across tax periods breach separate limitation requirements, permitting fresh period-compliant proceedings where lawfully availab...
Bank-account freezing under anti-money-laundering law requires recorded reasons; writ review remains available despite an alternative statutory remedy...
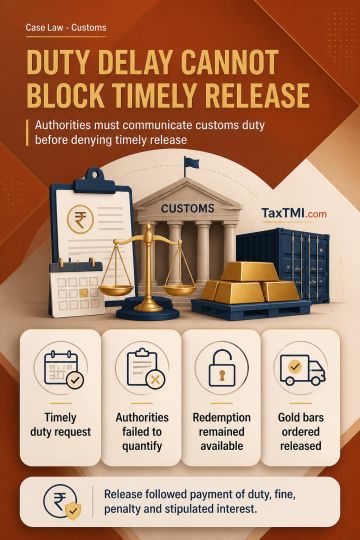
Redemption of confiscated goods remains available where the person seeking redemption timely requests quantification of applicable customs duty, but the authorities neither quantify it nor clarify that redemption fine and penalty may be paid independently. Failure to complete redemption within the stipulated period cannot then be attributed solely to the claimant, notwithstanding that expiry ordinarily makes confiscation absolute. The High Court directed communication of duty and release of the gold bars after payment of duty, redemption fine, penalty and stipulated interest.
Redemption of confiscated goods remains available where the person seeking redemption timely requests quantification of applicable customs duty, but the authorities neither quantify it nor clarify that redemption fine and penalty may be paid independently. Failure to complete redemption within the stipulated period cannot then be attributed solely to the claimant, notwithstanding that expiry ordinarily makes confiscation absolute. The High Court directed communication of duty and release of the gold bars after payment of duty, redemption fine, penalty and stipulated interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935