Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
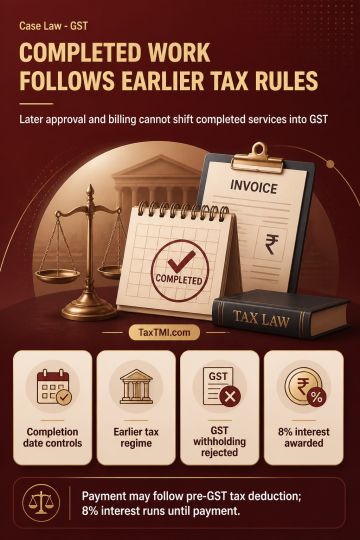
Services rendered and completed before the GST appointed day remain subject, if taxable, to the erstwhile Service Tax regime even where work approval and billing occur after GST commenced. Post-facto approval and subsequent invoices do not alter the date of supply or bring an already completed manpower service within the WBGST Act. Payment cannot be withheld solely for non-compliance with GST formalities; the payable amount may be released after deduction of applicable pre-GST tax. Where a genuine taxability dispute and pending civil proceedings contribute to delayed payment, interest may be set at the prevailing banking rate; interest at 8% per annum was directed from bill submission until payment.
Services rendered and completed before the GST appointed day remain subject, if taxable, to the erstwhile Service Tax regime even where work approval and billing occur after GST commenced. Post-facto approval and subsequent invoices do not alter the date of supply or bring an already completed manpower service within the WBGST Act. Payment cannot be withheld solely for non-compliance with GST formalities; the payable amount may be released after deduction of applicable pre-GST tax. Where a genuine taxability dispute and pending civil proceedings contribute to delayed payment, interest may be set at the prevailing banking rate; interest at 8% per annum was directed from bill submission until payment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881