Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
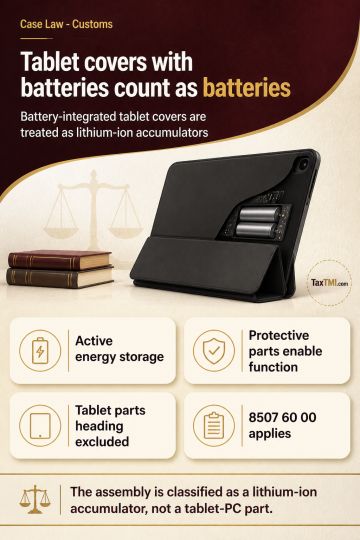
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Page of 4886
Press 'Enter' after typing page number.
781 to 800 of 97705 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Input tax credit recorded under incorrect CGST and SGST heads in GSTR-3B, despite corresponding IGST credit appearing in GSTR-2A, remained subject to reversal. Eligible IGST-related credit was allowed after record verification, but the remaining CGST and SGST credit was not supported by new facts or records justifying interference. Precedents cited for the taxpayer were inapplicable because of differing factual circumstances. The Tribunal sustained reversal of the disputed credit, together with consequential interest and penalty, and confirmed dismissal of the appeal.
Input tax credit recorded under incorrect CGST and SGST heads in GSTR-3B, despite corresponding IGST credit appearing in GSTR-2A, remained subject to reversal. Eligible IGST-related credit was allowed after record verification, but the remaining CGST and SGST credit was not supported by new facts or records justifying interference. Precedents cited for the taxpayer were inapplicable because of differing factual circumstances. The Tribunal sustained reversal of the disputed credit, together with consequential interest and penalty, and confirmed dismissal of the appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886