Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
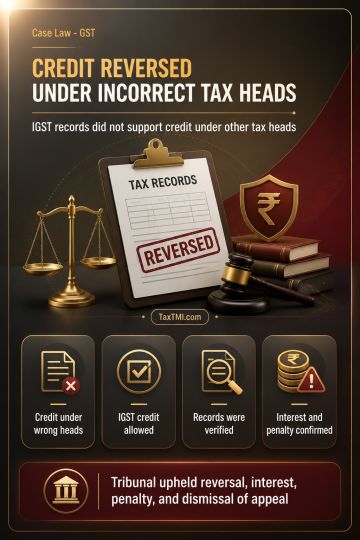
Input tax credit recorded under incorrect CGST and SGST heads in GSTR-3B, despite corresponding IGST credit appearing in GSTR-2A, remained subject to reversal. Eligible IGST-related credit was allowed after record verification, but the remaining CGST and SGST credit was not supported by new facts or records justifying interference. Precedents cited for the taxpayer were inapplicable because of differing factual circumstances. The Tribunal sustained reversal of the disputed credit, together with consequential interest and penalty, and confirmed dismissal of the appeal.
Input tax credit recorded under incorrect CGST and SGST heads in GSTR-3B, despite corresponding IGST credit appearing in GSTR-2A, remained subject to reversal. Eligible IGST-related credit was allowed after record verification, but the remaining CGST and SGST credit was not supported by new facts or records justifying interference. Precedents cited for the taxpayer were inapplicable because of differing factual circumstances. The Tribunal sustained reversal of the disputed credit, together with consequential interest and penalty, and confirmed dismissal of the appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881