Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
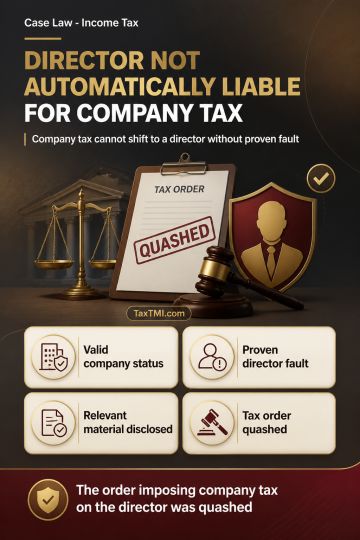
Section 179 cannot fasten unrecovered company tax on a director of an unlisted public company merely because shareholding is concentrated or shares were not publicly offered. Public or private status depends on the Memorandum and Articles of Association; lifting the corporate veil requires exceptional facts, which were absent. Liability also requires a finding that non-recovery was attributable to the director's gross neglect, misfeasance or breach of duty, assessed against the director's role in the non-recovery. Reliance on an undisclosed adverse statement while disregarding relevant material from the director breached natural justice. The order imposing the company's tax liability on the director was quashed.
Section 179 cannot fasten unrecovered company tax on a director of an unlisted public company merely because shareholding is concentrated or shares were not publicly offered. Public or private status depends on the Memorandum and Articles of Association; lifting the corporate veil requires exceptional facts, which were absent. Liability also requires a finding that non-recovery was attributable to the director's gross neglect, misfeasance or breach of duty, assessed against the director's role in the non-recovery. Reliance on an undisclosed adverse statement while disregarding relevant material from the director breached natural justice. The order imposing the company's tax liability on the director was quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935