Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Page of 4881
Press 'Enter' after typing page number.
621 to 640 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
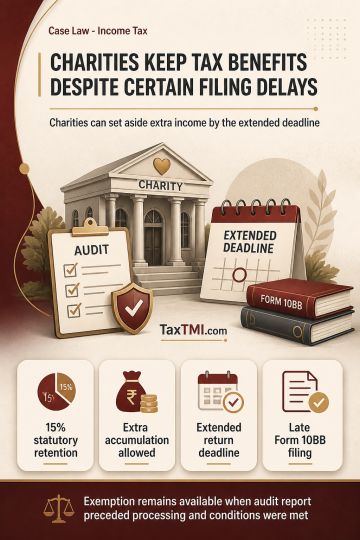
Statutory accumulation of 15 per cent of charitable income under section 11(1)(a) is distinct from further accumulation under section 11(2). Where charitable eligibility and application of income to charitable objects are satisfied, the statutory retention remains available. Accumulation beyond that limit may be claimed where Form No. 10 is furnished by the extended due date for filing the return, rather than only by the original due date. Charitable exemption should not be denied solely because Form No. 10BB was electronically furnished late if the audit report was available before return processing and substantive exemption conditions were met.
Statutory accumulation of 15 per cent of charitable income under section 11(1)(a) is distinct from further accumulation under section 11(2). Where charitable eligibility and application of income to charitable objects are satisfied, the statutory retention remains available. Accumulation beyond that limit may be claimed where Form No. 10 is furnished by the extended due date for filing the return, rather than only by the original due date. Charitable exemption should not be denied solely because Form No. 10BB was electronically furnished late if the audit report was available before return processing and substantive exemption conditions were met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881