Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Page of 4881
Press 'Enter' after typing page number.
781 to 800 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
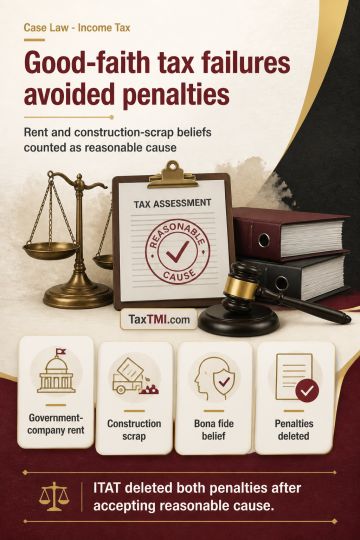
Reasonable cause under section 273B excused failures to deduct tax from rent paid to a Government-owned company and to collect tax on construction scrap. ITAT accepted the payer's bona fide belief that the Government-owned payee was a Government instrumentality not subject to tax deduction at source, treating that belief as reasonable cause; the rent-related penalty was deleted. ITAT also accepted the bona fide understanding that scrap arising from construction activities, including cutting and moulding materials, was not scrap covered by the tax-collection provisions because construction was not treated as manufacturing. The related tax-collection penalty was likewise deleted.
Reasonable cause under section 273B excused failures to deduct tax from rent paid to a Government-owned company and to collect tax on construction scrap. ITAT accepted the payer's bona fide belief that the Government-owned payee was a Government instrumentality not subject to tax deduction at source, treating that belief as reasonable cause; the rent-related penalty was deleted. ITAT also accepted the bona fide understanding that scrap arising from construction activities, including cutting and moulding materials, was not scrap covered by the tax-collection provisions because construction was not treated as manufacturing. The related tax-collection penalty was likewise deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881