Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
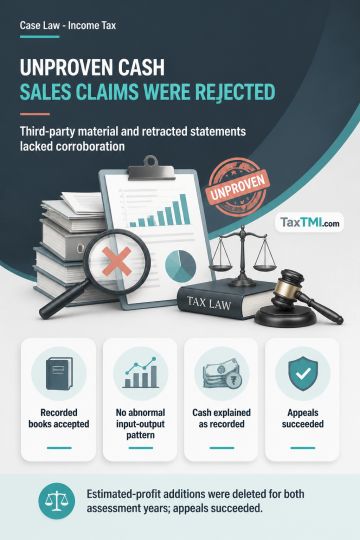
Uncorroborated third-party search material cannot support additions for alleged cash coal purchases where recorded sales, coal consumption, production and books remain accepted, and no abnormal input-output pattern or independent evidence is established. Estimated profit from hypothetical unrecorded coal sales was therefore deleted. Likewise, a retracted statement alleging under-invoicing of mill scale sales, coupled with CCTV-based presumptions, is insufficient where the cash is explained as recorded and no independent evidence confirms suppressed sales. The estimated-profit additions for alleged mill scale suppression were deleted for both assessment years, and the appeals succeeded.
Uncorroborated third-party search material cannot support additions for alleged cash coal purchases where recorded sales, coal consumption, production and books remain accepted, and no abnormal input-output pattern or independent evidence is established. Estimated profit from hypothetical unrecorded coal sales was therefore deleted. Likewise, a retracted statement alleging under-invoicing of mill scale sales, coupled with CCTV-based presumptions, is insufficient where the cash is explained as recorded and no independent evidence confirms suppressed sales. The estimated-profit additions for alleged mill scale suppression were deleted for both assessment years, and the appeals succeeded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881