Functional comparability under TNMM supported exclusion of ITeS comparables with R&D, intangibles, diversified operations, or unavailable segmental da...
Functional comparability governs selection of support-service and IT-enabled service comparables, with verification required for unresolved data and m...
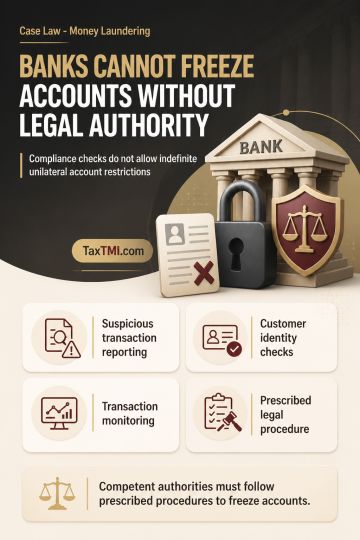
Bank account freezing requires statutory authority; anti-money-laundering compliance and KYC monitoring do not permit unilateral indefinite restrictio...
Section 144C requires a draft assessment order before a final assessment order is made against an eligible foreign company where a prejudicial variation is proposed. The draft-order procedure enables the taxpayer to accept the variation or seek directions from the Dispute Resolution Panel before finalisation. Non-compliance is a jurisdictional defect rather than a curable procedural irregularity, and vitiates the final assessment order. Applying this principle, the assessment order was set aside for failure to issue a draft order; the taxpayer's cross-objection succeeded and the Revenue's merits appeal became infructuous.
Section 144C requires a draft assessment order before a final assessment order is made against an eligible foreign company where a prejudicial variation is proposed. The draft-order procedure enables the taxpayer to accept the variation or seek directions from the Dispute Resolution Panel before finalisation. Non-compliance is a jurisdictional defect rather than a curable procedural irregularity, and vitiates the final assessment order. Applying this principle, the assessment order was set aside for failure to issue a draft order; the taxpayer's cross-objection succeeded and the Revenue's merits appeal became infructuous.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891