Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
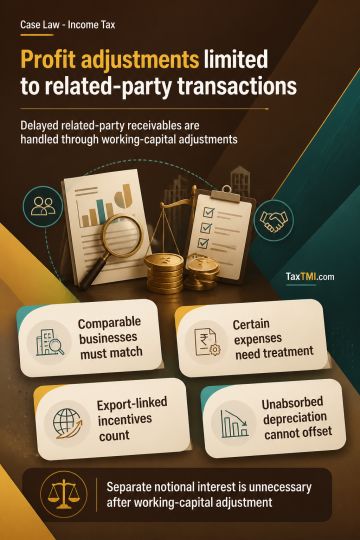
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
A prior Advance Pricing Agreement remains persuasive for...
Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adjustment.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
A prior Advance Pricing Agreement remains persuasive for transfer pricing benchmarking outside its covered years where the transaction and functions, assets and risks profile continue; departure requires material differences in those factors or economic circumstances. In software-distribution comparability, functional similarity takes priority over turnover, and turnover-based exclusion requires a demonstrated material effect on operating margins. Comparable companies with related-party transactions exceeding the applicable threshold cannot reliably serve as uncontrolled benchmarks without demonstrable adjustments. Under TNMM, no transfer pricing adjustment is warranted where the tested party's operating margin falls within the applicable arm's length range after the comparable set is finalised.
A prior Advance Pricing Agreement remains persuasive for transfer pricing benchmarking outside its covered years where the transaction and functions, assets and risks profile continue; departure requires material differences in those factors or economic circumstances. In software-distribution comparability, functional similarity takes priority over turnover, and turnover-based exclusion requires a demonstrated material effect on operating margins. Comparable companies with related-party transactions exceeding the applicable threshold cannot reliably serve as uncontrolled benchmarks without demonstrable adjustments. Under TNMM, no transfer pricing adjustment is warranted where the tested party's operating margin falls within the applicable arm's length range after the comparable set is finalised.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881