RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Page of 4888
Press 'Enter' after typing page number.
1061 to 1080 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
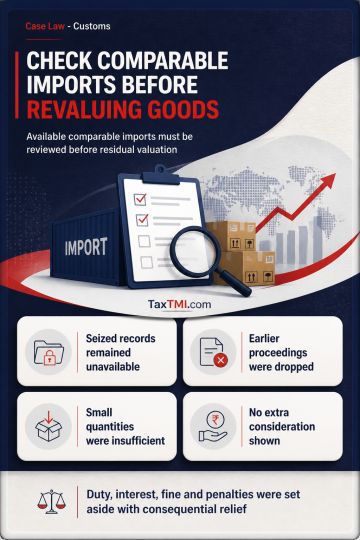
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888