SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
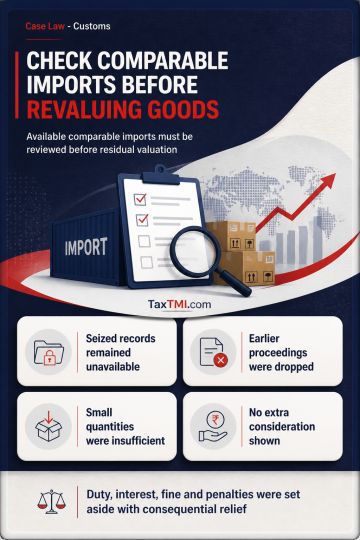
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888