Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
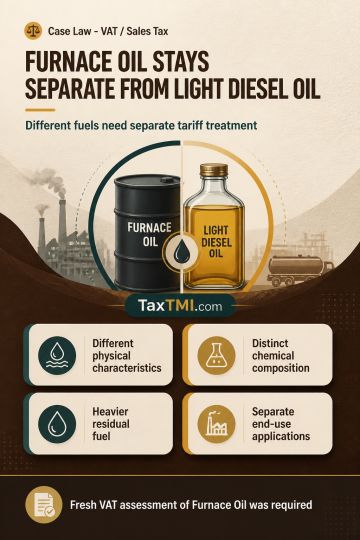
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894