Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
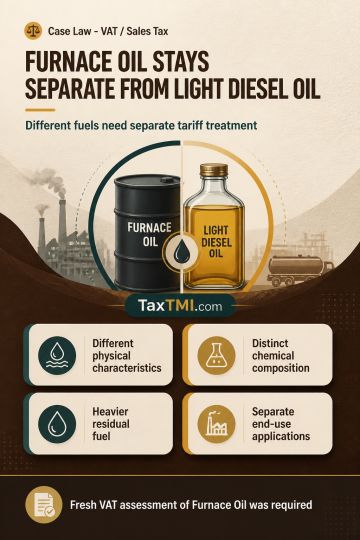
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894