Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
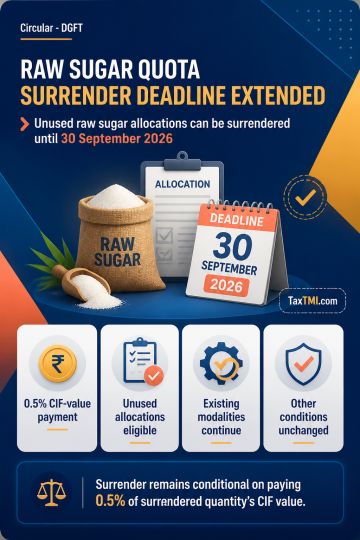
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886