Self-assessed import entries remain appealable, while bona fide classification disputes without misdeclaration cannot justify confiscation or penaltie...
Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Customs offence disqualification excludes civil contraventions, preventing refusal of a private bonded warehouse licence based solely on monetary pena...
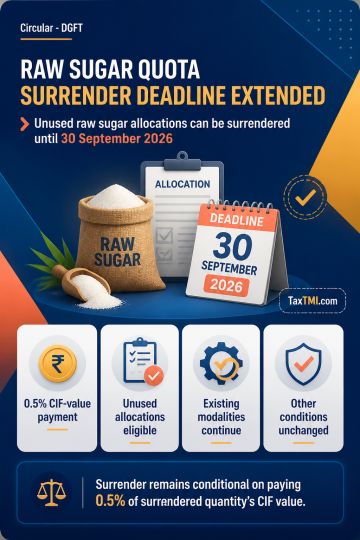
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883