Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
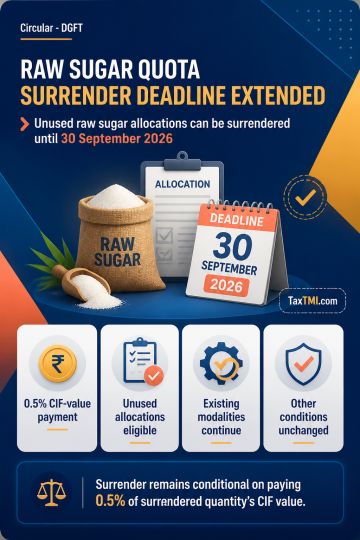
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886