Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
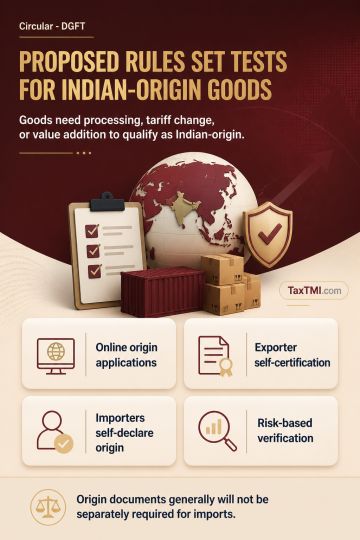
Proposed non-preferential Rules of Origin would require exported goods using imported inputs to undergo processing beyond specified minimal operations before being treated as Indian-origin. Exporters would apply online for non-preferential Certificates of Origin, while manufacturer exporters holding Status Holder recognition could self-certify qualifying goods. Back-to-back certificates could support re-exports, trans-shipment and merchanting trade for foreign-origin goods. For imports, agricultural goods would generally be origin-determined by wholly obtained or produced status, subject to a de-minimis tolerance, while other goods would require either a change in tariff heading or prescribed value addition. Importers would self-declare origin; separate origin documents would generally not be required, with risk-based verification permitted.
Proposed non-preferential Rules of Origin would require exported goods using imported inputs to undergo processing beyond specified minimal operations before being treated as Indian-origin. Exporters would apply online for non-preferential Certificates of Origin, while manufacturer exporters holding Status Holder recognition could self-certify qualifying goods. Back-to-back certificates could support re-exports, trans-shipment and merchanting trade for foreign-origin goods. For imports, agricultural goods would generally be origin-determined by wholly obtained or produced status, subject to a de-minimis tolerance, while other goods would require either a change in tariff heading or prescribed value addition. Importers would self-declare origin; separate origin documents would generally not be required, with risk-based verification permitted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891