Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    E-invoice procedural lapse alone cannot sustain detention penalty where transport records establish a genuine taxable supply without tax evasion.
    Tariff classification of oversized kitchen exhaust hoods places integral-fan units in the residual entry rather than fans.
    Defence end-use customs exemption covers missile-warning components, but each import requires prescribed certification and customs verification.
    Fraud-based GST recovery requires show cause notices to state foundational facts, not merely recite statutory grounds.
    GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
    Expiry of seizure period requires release of seized mobile phones and debit cards where no extension order exists.
    Cash seizure under GST search powers was impermissible, requiring interest on refunded cash and release of retained devices.
    Electronic Cash Ledger balances do not discharge GST liabilities until debit, sustaining delayed-payment interest and recovery.
    Doctrine of merger preserves writ review after time-barred GST registration appeal and enables conditional registration restoration.
    Input tax credit requires supplier tax payment; insolvency proceedings do not remove the recipient's statutory condition.
    Retrospective input tax credit relief protects timely GSTR-3B claims from limitation-based denial and consequential liabilities.
    Blocked Input Tax Credit Requires Specific Exclusions, While Interest Applies Only to Credit Actually Utilised
    E-way bill vehicle-number mismatch raises competing views on tax-evasion intent and penalty where commercial records identify the correct vehicle.
    Subsequent-Year Transaction Inclusion Invalidates Cash-Deposit Assessment Where Revision Failed to Address the Assessee's Material Challenge
    Bank investment revaluation and non-rural bad-debt deductions remain allowable despite rural doubtful-debt provisions under settled tax principles.
    Deemed acquisition of undeclared foreign assets requires assessment in the year following the first statutory notice.
    Deemed search date determines whether post-reform section 153C notices and consequential assessments remain legally valid.
    Reasonable cause for non-filing of a return supported deletion of salary-income misreporting penalty despite tax deducted at source.
    Treaty employment income exemption protects Vietnam-earned salary despite Indian payroll, bank receipt, and tax withholding.
    Prospective operation of exemption notifications prevents later amendments from blocking provisional release of pre-amendment imported machinery.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Duty exemption for durable containers imported under the...

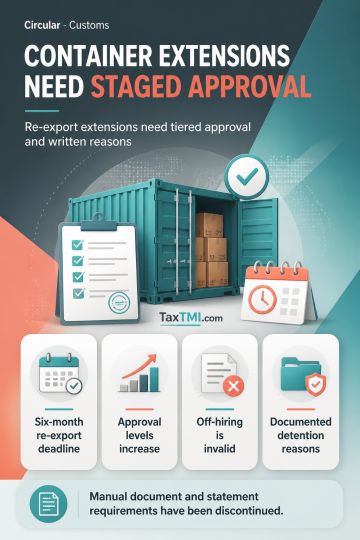
Container re-export extensions follow a tiered approval process; off-hiring is invalid, while detention-related requests require documented reasons.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Customs September 15, 2026 Circulars
Duty exemption for durable containers imported under the specified customs notification remains conditional on execution of a bond by the importer or shipping agent and re-export within six months from landing. Re-export extensions may be granted for three months by the Assistant/Deputy Commissioner, followed by two further six-month extensions at successively higher approval levels; any rejection requires written, case-specific reasons. Off-hiring is not a valid ground for extension. Where cargo is detained for examination or investigation, it should be destuffed and stored so containers can be re-exported; extensions for laden containers awaiting clearance or auction may be considered on a substantiated request. Manual document and statement submission requirements have been discontinued.

Topics

Acts Income Tax