Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
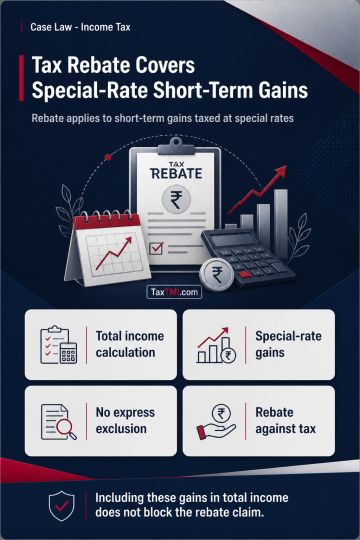
Rebate on tax liability computed on total income extends to short-term capital gains taxed at special rates. The rebate provision does not distinguish between income taxed at normal rates and such gains, while the special-rate provision and the optional tax-regime provision contain no express exclusion. Consequently, inclusion of short-term capital gains in total income does not, by itself, prevent the taxpayer from claiming the rebate against tax payable on those gains.
Rebate on tax liability computed on total income extends to short-term capital gains taxed at special rates. The rebate provision does not distinguish between income taxed at normal rates and such gains, while the special-rate provision and the optional tax-regime provision contain no express exclusion. Consequently, inclusion of short-term capital gains in total income does not, by itself, prevent the taxpayer from claiming the rebate against tax payable on those gains.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881