Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
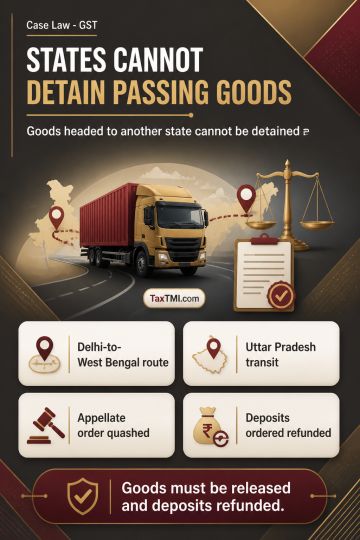
State GST authorities cannot detain or seize goods merely passing through their territory during inter-State transit where the goods are destined for another State. The territorial power to detain and seize does not extend to goods moving from Delhi to West Bengal solely because they transit Uttar Pradesh. On that basis, the appellate order upholding detention was quashed, the goods were directed to be released, and any amount deposited was directed to be refunded.
State GST authorities cannot detain or seize goods merely passing through their territory during inter-State transit where the goods are destined for another State. The territorial power to detain and seize does not extend to goods moving from Delhi to West Bengal solely because they transit Uttar Pradesh. On that basis, the appellate order upholding detention was quashed, the goods were directed to be released, and any amount deposited was directed to be refunded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881