Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Page of 4881
Press 'Enter' after typing page number.
781 to 800 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
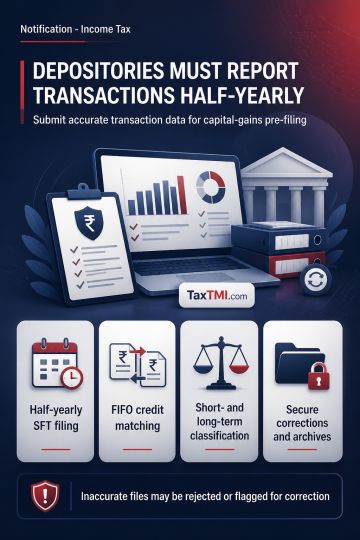
Depositories must file SFT-2517 for demat-account transactions half-yearly through the prescribed SFTP process, with a signed and verified control statement, to support pre-filling of capital gains information. Transaction summaries must cover user-initiated debits, identify corresponding credits using the FIFO method, and determine estimated sale consideration and acquisition cost using prescribed weighted-average or end-of-day values. Assets must be classified as short- or long-term under specified holding periods; market-linked debentures and specified mutual funds are always short-term. Depositories must provide reported information to account holders for AIS reconciliation, correct or delete inaccurate data, and maintain information-security and archival procedures. Non-compliant data files are rejected or flagged for correction.
Depositories must file SFT-2517 for demat-account transactions half-yearly through the prescribed SFTP process, with a signed and verified control statement, to support pre-filling of capital gains information. Transaction summaries must cover user-initiated debits, identify corresponding credits using the FIFO method, and determine estimated sale consideration and acquisition cost using prescribed weighted-average or end-of-day values. Assets must be classified as short- or long-term under specified holding periods; market-linked debentures and specified mutual funds are always short-term. Depositories must provide reported information to account holders for AIS reconciliation, correct or delete inaccurate data, and maintain information-security and archival procedures. Non-compliant data files are rejected or flagged for correction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881